International Business Machines Corporation IBM experienced slower momentum in its Software business in the second quarter of 2026. Software revenues increased 5% year over year to $7.8 billion, but organic revenue growth was flat. The weakness was primarily in the Transaction Processing business. Revenues from this business declined 8% year over year.
The company attributed the shortfall primarily to customers shifting capital spending toward servers, storage and memory to secure supply-constrained infrastructure ahead of anticipated price increases. As a result, several large software deals didn’t close within the expected timeframe.
However, despite the slowdown, it is to be noted that approximately 80% of annual Software revenues is recurring. Red Hat remains a key growth engine for IBM. Hybrid Cloud revenues increased 11% in the second quarter, while OpenShift ARR reached $2.2 billion. IBM’s Data business was another growth engine. Revenues increased 19% year over year.
The acquisitions of HashiCorp and Confluent have strengthened IBM’s capabilities in automation, data and hybrid-cloud environments. Despite the revenue shortfall, IBM managed to expand Software segment profit. Software segment profit rose 9% to $2.5 billion, while the segment margin increased 110 basis points to 32.2%. Strong focus on productivity is helping to offset the pressure coming from slower revenue growth.
How Are Competitors Faring?
IBM faces competition from Microsoft Corporation MSFT and Oracle Corporation ORCL. In the June quarter, Microsoft’s Productivity & Business Processes segment generated $37.8 billion in revenues, which grew 14% year over year. Microsoft 365 Commercial cloud revenues increased 14% on a reported basis, or 16% when adjusted for a prior-year comparable that had benefited from two points of in-period revenue recognition.
Oracle’s cloud revenues (SaaS plus IaaS) surged 47% in USD and 46% in cc to $9.9 billion, demonstrating that cloud remains the primary driver of Oracle’s growth trajectory. However, Software revenues were down 2% to $6.8 billion, reflecting customers’ continuing migration from on-premises software to the Cloud.
IBM’s Price Performance, Valuation & Estimates
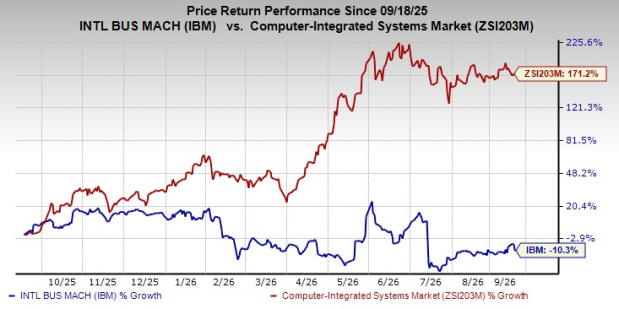
IBM shares have lost 10.3% over the past year against the industry’s growth of 171.2%.
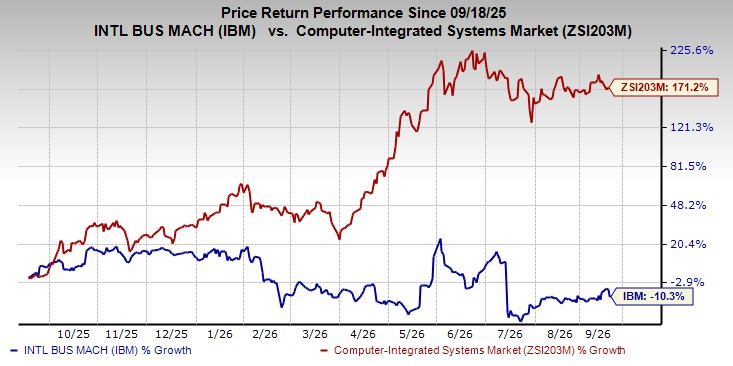
Image Source: Zacks Investment Research
From a valuation standpoint, IBM trades at a forward price-to-sales ratio of 3.09, below the industry average of 4.6.
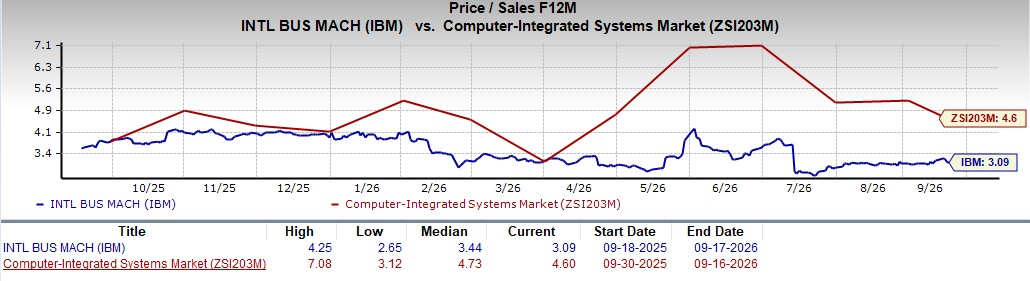
Image Source: Zacks Investment Research
Earnings estimates for 2026 have increased 0.7% to $12.33 over the past 60 days, while the same for 2027 have decreased 0.6% to $13.22.
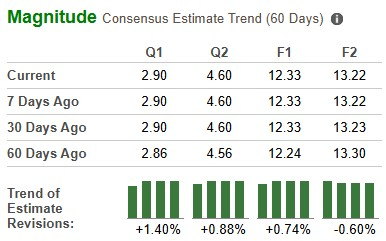
Image Source: Zacks Investment Research
IBM currently carries a Zacks Rank #3 (Hold). You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
Zacks’ Research Chief Names “Stock Most Likely to Double”
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
Of course, all our elite picks aren’t winners, but this one could far surpass earlier Zacks’ Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners Up
International Business Machines Corporation (IBM) : Free Stock Analysis Report
Microsoft Corporation (MSFT) : Free Stock Analysis Report
Oracle Corporation (ORCL) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.