Cisco offers a warning as the Mag 7 pour billions into AI.
Listen to the audio version of this article (generated by AI).
Hello, Reader.
While trick-or-treaters fill neighborhoods across the U.S. tonight, our neighbors to the south are preparing for another celebration: Día de los Muertos, or Day of the Dead.
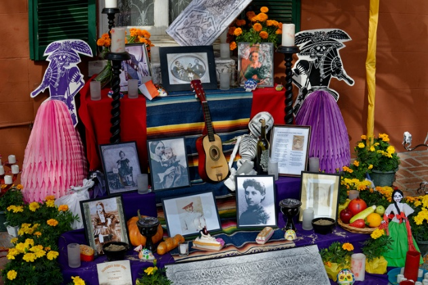
On the eve of this Mexican holiday, those who celebrate are preparing their ofrendas – altars adorned with images and mementos to honor loved ones who have passed away.
It is a cultural tradition rooted in remembrance and the celebration of the cyclical nature of life and death.
Now, I have a feeling that if the market were to participate in this holiday, its ofrenda would include the once-mighty Cisco Systems Inc. (CSCO).
In its day, Cisco was the darling of the internet boom. It went public in 1990 with a $224 million valuation. By March 2000, it had grown into a $550 billion giant – briefly making it one of the most valuable companies in the world.
Also on the ofrenda would sit RCA, the radio pioneer of the Roaring Twenties. As radio took over American living rooms, RCA’s stock rose about 200-fold over the decade.
But both of these market legends eventually became symbols of booms gone bust. Cisco’s shares fell nearly 90% between March 2000 and late 2002 as the dot-com bubble burst. And RCA’s stock plunged about 98% between 1929 and 1932, after radio mania gave way to the Great Crash.
Neither company’s technology necessarily died. Radio and the internet went on to change the world.
What didn’t last was the dominance of the companies that built them.
And that’s exactly why it’s important to remember the companies that once ruled the market.
I expect we’ll see this pattern play out with AI, too. While demand for AI is clearly real, there remains an important question: Which companies will remain standing once excitement – and investment – fades? History shows that building a world-changing technology doesn’t guarantee lasting success for the businesses behind it.
That question is especially relevant as the biggest AI players, those in the Magnificent Seven who once ruled the stock market, report their most recent earnings.
In today’s Smart Money, I’ll share the latest quarterly earnings from the Mag 7 companies and what they reveal about investing in AI today. Hint: the best investments to make now are not the Mag 7 stocks that are spending billions to build AI data centers, but in the kinds of companies that can profit from AI without having to foot the construction bill.
The Price of AI Is Falling, but the Cost of Building It Isn’t
Tesla Inc. (TSLA) and Meta Platforms Inc. (META) kicked things off after the market closed last Wednesday, October 21.
Tesla’s revenue came in flat at $28.05 billion, yet its capital expenditures (CapEx) – the money a company spends on physical assets like factories, chips and data centers – more than doubled to $4.7 billion to fund its robotaxis, Optimus robots, and AI ambitions. The carmaker is now an AI builder. But for now, Tesla’s AI ambitions are costing more than they’re bringing in.
Meta’s revenue rose 26% to $64.6 billion, topping Wall Street’s estimate. But CapEx climbed to $34.9 billion for the quarter, and Meta raised its 2026 CapEx outlook to between $135 billion and $145 billion. Free cash flow – the cash left over after those investments – turned negative, at -$2.1 billion. So, the payoff from its AI investments has yet to catch up with the cost.
This past Wednesday, Alphabet Inc. (GOOGL) and Microsoft Corp. (MSFT) reported after the close.
Alphabet’s earnings per share came in at $2.67, below Wall Street’s $3.02 estimate, while revenue of $127.58 billion fell just short of the $128.22 billion estimate. Google Cloud revenue rose 103% to $30.7 billion. But CapEx also more than doubled to $51.4 billion, and free cash flow came in at -$9.1 billion.
Finance chief Anat Ashkenazi added that CapEx will “increase significantly in 2027.” The next day, the stock fell nearly 13% – its worst single-day drop ever. So, Google Cloud’s explosive growth suggests strong demand for AI and cloud services. But spending is rising just as quickly, and negative cash flow leaves investors questioning whether the investment is paying off.
Microsoft, by contrast, reported quarterly revenue growth of 19% and earnings per share of $4.89, beating expectations. Azure cloud revenue grew 48%. CapEx rose about 30% to $45.2 billion – less than investors expected – and free cash flow stayed positive at $18.6 billion. Microsoft appears to be making the strongest case that AI growth can justify the spending. But while positive cash flow is encouraging, it remains to be seen whether that growth will generate enough returns to justify the investment.
Finally, Amazon.com Inc. (AMZN) reported on Thursday after markets closed. Its Amazon Web Services (AWS) cloud business grew 39% to $46 billion, its fastest pace in nearly five years. But revenue and earnings came in slightly below estimates, and CapEx jumped to $77.3 billion – well above the roughly $59 billion analysts expected. Over the past 12 months, Amazon’s free cash flow was -$42.4 billion, and management signaled it will spend even more in 2027. Shares fell about 7% in early trading on Friday. With spending far outpacing expectations and free cash flow deep in the red, Amazon still has a lot to prove before its AI investments pay off.
The Builders Won’t Rule Forever
The pattern here is hard to miss. AI revenue is real, and it’s growing fast. But spending is growing faster. Alphabet, Meta, and Amazon all spent more cash than their businesses brought in. And none of them plan to slow down.
Cisco and RCA were right about the future of their industries. But investors who paid top dollar for the companies building that infrastructure waited years – even decades – to break even, if they ever did. Cisco’s stock didn’t return to its 2000 high until December 2025.
I expect the Mag 7 – all of which are AI Builders– to face a similar reckoning. As AI gets cheaper, the hundreds of billions they’re pouring into data centers and chips will become harder to earn back. And the market is already starting to notice, punishing the biggest spenders and rewarding restraint.
Meanwhile, a different group stands to benefit: the companies that apply AI. These businesses don’t need to build data centers or design chips. They simply put AI to work – cutting costs, improving products, and growing profits. Every time AI gets cheaper, their opportunity gets bigger.
The biggest winners of the internet era weren’t the companies building its plumbing. They were the ones that used it. I believe the same will be true for AI.
My Fry’s Investment Report portfolio reaches well beyond the biggest names in AI. It includes a drive-thru beverage chain, multiple healthcare and biotech companies, and leaders in design and retail – businesses with different ways to benefit from changing technology and consumer demand.
Check out the full portfolio – and learn how to join us here.
I don’t expect to see the Mag 7 on the market’s ofrenda next year. But history shows that the builders of a technological revolution aren’t always the ones who get to celebrate it.
The real opportunities may shift to companies that know how to put the technology to work – and turn it into lasting profits.
Regards,
Eric Fry
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.