The TJX Companies, Inc. TJX combines rising sales, higher earnings guidance and a larger store-expansion runway with a valuation that remains above key benchmarks. That mix keeps the investment case tied closely to execution.
Second-quarter results showed broad strength outside Marmaxx, while cash generation remained substantial. The question is whether those advantages can support the stock’s premium as merchandising and cost pressures continue.
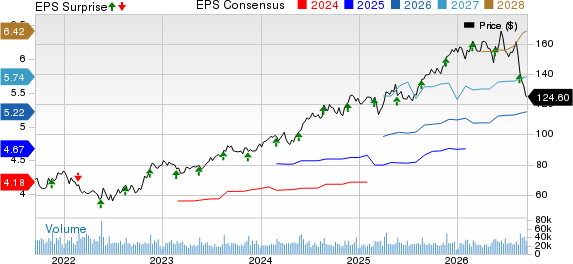
The TJX Companies, Inc. Price, Consensus and EPS Surprise

The TJX Companies, Inc. price-consensus-eps-surprise-chart | The TJX Companies, Inc. Quote
TJX’s Growth Case Extends Beyond Fiscal 2027
Management expects fiscal 2027 comparable sales to rise 3% to 4% and consolidated sales of $63.4 billion to $63.8 billion, up 5% to 6%. TJX also raised adjusted earnings guidance to $5.15 to $5.20 per share from $5.08 to $5.15.
The longer runway comes from stores. TJX lifted its long-term global store target by 500 locations to 7,500 and plans to accelerate annual store growth to 4% beginning in fiscal 2028.
Off-price peers show that the category remains active. Ross Stores, Inc. ROST reported a 10% comparable-store sales gain and 13% total sales growth in its fiscal second quarter. Burlington Stores, Inc. BURL posted 2% comparable-store sales growth and an 11% increase in total sales for its fiscal second quarter.
TJX’s Premium Valuation Raises the Hurdle
TJX’s forward 12-month price-to-sales ratio is 2.06, above the Zacks sub-industry’s 1.58 and the stock’s five-year median of 1.95. The premium means investors are paying more than the company’s recent historical midpoint and its industry comparison on this measure.
The stock’s first-year forward P/E is 33.41. With that valuation, continued earnings delivery, Marmaxx improvement and progress toward the larger store target become more important to sustaining the investment case.
TJX Has Cash to Fund Growth and Shareholder Returns
Operating cash flow reached $3.3 billion in the first half of fiscal 2027, up from $2.2 billion a year earlier. TJX ended the second quarter with about $6 billion in cash and expects fiscal 2027 capital spending of about $2.2 billion to $2.3 billion.
The company also returned $2.4 billion to shareholders in the first half, including $1.4 billion of share repurchases and $1 billion of dividends. Management continues to expect fiscal 2027 repurchases of about $2.75 billion to $3 billion.
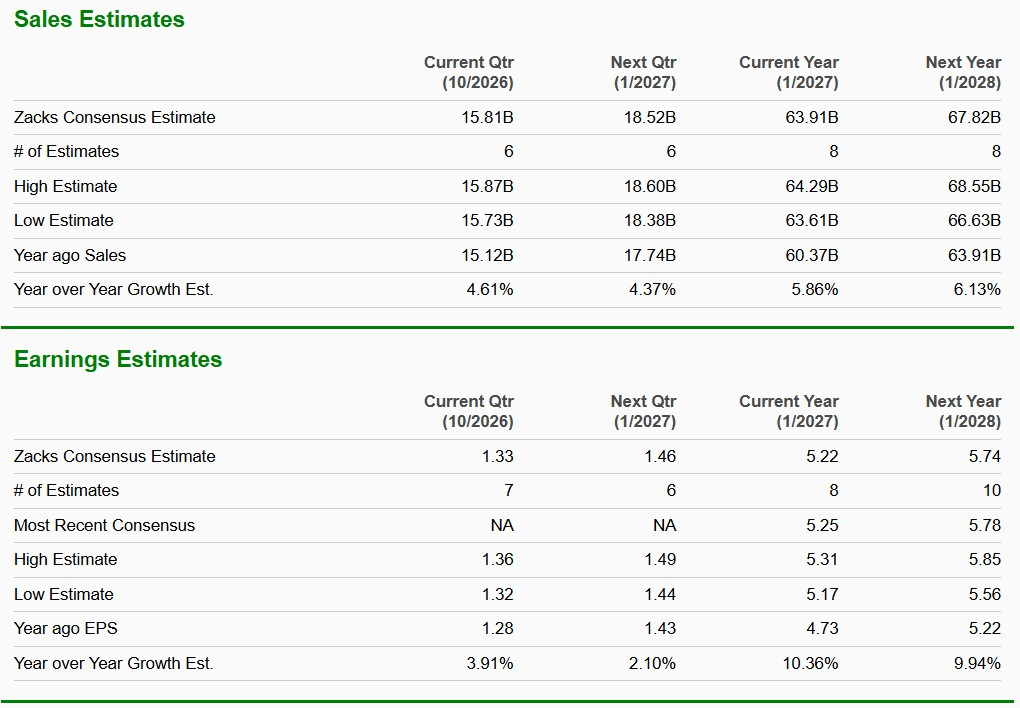
Image Source: Zacks Investment Research
TJX Still Faces Execution and Cost Risks
Marmaxx comparable sales increased just 1% in the second quarter. Management described the merchandise-mix issues as self-inflicted and within its control, while reporting improvement at the start of the third quarter.
Costs remain another constraint. Adjusted selling, general and administrative costs were 19.7% of sales, 20 basis points unfavorable year over year because of higher store wage and payroll costs. Third-quarter adjusted gross margin is projected at 32.1% to 32.2%, down 40-50 basis points, primarily because of higher fuel costs.
TJX’s Signals Favor Growth More Than Value
TJX offers a constructive growth and cash-flow profile, but the premium valuation leaves less room for execution misses. The near-term case therefore rests on whether earnings delivery, Marmaxx improvement and store expansion continue to offset cost pressure.
TJX currently carries a Zacks Rank #2 (Buy). The rank reflects a favorable short-term earnings-estimate-revision signal over a one- to three-month horizon, while the Growth Score of B, Momentum Score of B and VGM Score of B add support for investors emphasizing those styles. You can see the complete list of today’s Zacks #1 Rank (Strong Buy) stocks here.
The Value Score of D points to a less attractive valuation profile. That contrast fits the broader setup: TJX has favorable growth and momentum signals, but valuation remains the main counterweight to the investment case.
Zacks’ Research Chief Names “Stock Most Likely to Double”
Our team of experts has just released the 5 stocks with the greatest probability of gaining +100% or more in the coming months. Of those 5, Director of Research Sheraz Mian highlights the one stock set to climb highest.
This innovative software-as-a-service firm upped its user base +22% year over year. That rate is increasing and margins are expanding as AI efficiencies take effect. Of course, all our elite picks aren’t winners, but this one could far surpass earlier Zacks’ Stocks Set to Double like D-Wave Quantum, which shot up +680.1%.
Free: See Our Top Stock And 4 Runners Up
The TJX Companies, Inc. (TJX) : Free Stock Analysis Report
Ross Stores, Inc. (ROST) : Free Stock Analysis Report
Burlington Stores, Inc. (BURL) : Free Stock Analysis Report
This article originally published on Zacks Investment Research (zacks.com).
5 Stocks Our Experts Predict Could Double In the Next Year
By submitting your email, you'll also get a free pivot & flow membership. A free daily market overview. You can unsubscribe at any time.